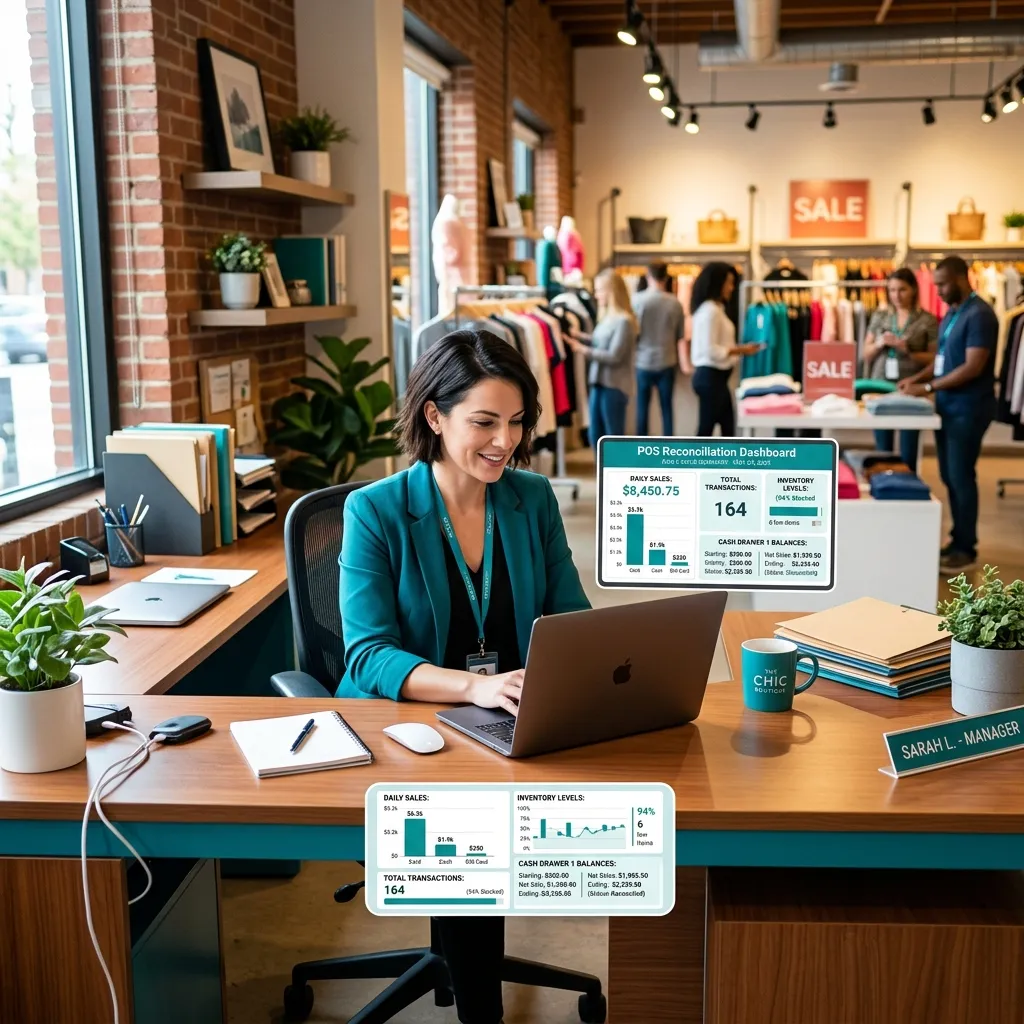
Outsourced financial reporting for retail businesses covers the end-to-end preparation of store-level P&L statements, IFRS 16 lease accounting schedules, inventory valuation reports, gross margin analysis by product category, shrinkage and markdown accounting, and IFRS-compliant annual financial statements. Rather than building an in-house finance function capable of handling multi-site retail complexity, retail operators engage Cred Books to deliver accurate reporting on a fixed monthly cycle.
Cred Books has delivered outsourced financial reporting for retail businesses across the UK, Ireland, Australia, New Zealand, the UAE, and the broader Asia-Pacific region. Our work spans independent boutique retailers, national chain operators, franchise networks, and direct-to-consumer brands managing both physical stores and online channels. Every client gets reporting that is fully compliant with IFRS and delivered in the format their investors, lenders, and franchisors require.
Retail financial reporting is not just about recording sales and purchases. IFRS 16 requires every store lease to be capitalised on the balance sheet. IAS 2 governs how inventory must be valued and when write-downs are required. Revenue recognition under IFRS 15 determines when a sale is recorded, how gift cards are treated, and how loyalty programme obligations are calculated. Gross margin analysis by product category requires a level of inventory system integration that standard bookkeeping services cannot provide.
Multi-site retail adds group consolidation complexity, franchise fee accounting obligations, and the need to benchmark each store's performance against the group average. Without store-level P&L statements, retailers cannot identify which sites are dragging group profitability or make evidence-based decisions on lease renewals and closures. Cred Books builds this analytical depth into every retail reporting engagement.
Monthly profit and loss statements prepared at individual store level, including revenue, cost of goods sold, gross margin, store operating costs, and contribution margin. Delivered alongside a group roll-up so management can benchmark stores and identify underperformers.
Right-of-use asset and lease liability schedules prepared for every store lease under IFRS 16. We calculate depreciation and interest charges, post journal entries monthly, and prepare the disclosures required in your annual financial statements.
Inventory valuation under FIFO or Weighted Average Cost as required by IAS 2. Monthly cost of goods sold reports reconciled to stock movements. Year-end inventory write-down calculations based on net realisable value assessments.
Gross margin reports segmented by product category, department, or brand. Identifies which product lines are generating margin and which are diluting the group average. Essential for buying decisions, promotional planning, and range rationalisation.
Systematic accounting for inventory shrinkage from theft, damage, and administrative error. Markdown write-downs applied when net realisable value falls below cost under IAS 2. Ensures your gross margin reports reflect the true cost of selling, not just the cost of buying.
Accurate accounting for brand royalty fees, marketing fund contributions, and area development obligations for franchised retail operators. We ensure all franchise costs are correctly classified and disclosed in the format required by your franchisor agreement.
Group-level consolidation for retailers operating multiple store entities. We manage inter-company eliminations, minority interest accounting, and IFRS 10 compliance. Both individual entity accounts and group consolidated statements delivered together.
Monthly cash flow statements and rolling 13-week cash flow forecasts. Retail working capital is heavily influenced by inventory cycles, supplier payment terms, and seasonal trading patterns. We model all of these into a forecast that management can actually use.
Full statutory financial statements under IFRS, including IFRS 16 lease disclosures, inventory accounting notes, related party transactions, and the notes required for audit sign-off. We coordinate directly with your auditors to ensure fieldwork completes on time.
A retailer with 50 stores and average lease terms of 5 years carries a significant right-of-use asset and lease liability on the balance sheet under IFRS 16. This affects reported net assets, debt-to-equity ratios, and the EBITDA metric that lenders use to assess covenant compliance. Getting IFRS 16 wrong creates restatement risk and can trigger covenant breaches on revolving credit facilities. Our outsourced financial reporting for retail businesses applies IFRS 16 correctly from onboarding day one.
An error in inventory valuation at period end flows directly into the cost of goods sold calculation and distorts the gross margin figure for every product category. If write-downs for slow-moving or damaged stock are not applied consistently, the balance sheet overstates assets and the P&L overstates profit. Cred Books applies IAS 2 inventory accounting at every period end, not just at year end.
Under IFRS 15, gift card income cannot be recognised when the card is sold. It must be deferred as a liability until the card is redeemed or the breakage estimate is applied. Similarly, loyalty points issued at point of sale reduce the revenue recognised on that transaction. Failing to account for these correctly overstates revenue in the period of sale and understates it in the period of redemption.
Retailers operating both physical stores and online channels must segment revenue, cost of goods sold, and gross margin by channel to understand the true profitability of each. Online fulfilment costs, return rates, and delivery charges make the online margin profile fundamentally different from the in-store margin. Blending these into a single revenue figure prevents any meaningful analysis of channel performance.
| Reporting Area | In-House Finance Team | Cred Books |
|---|---|---|
| IFRS 16 Lease Accounting | Often requires external specialist engagement | Included as standard; applied from onboarding |
| Store-Level P&L Reporting | Requires significant internal build time | Delivered from month one of the engagement |
| Inventory Valuation (IAS 2) | Applied at year end only in many businesses | Applied at every monthly period end |
| Gift Card Deferred Revenue | Frequently recognised on sale rather than redemption | Correct IFRS 15 treatment applied from day one |
| Monthly Reporting Speed | Often 15 to 20 working days after month end | Delivered by the 10th of the following month |
| Cost | High fixed salary cost plus benefits and leave | Fixed monthly fee with no hidden variable costs |
| Multi-Site Consolidation | Additional headcount needed per entity | Scalable across single stores to national chains |
Before IFRS 16, retailers kept all operating leases off the balance sheet, understating both assets and liabilities. Under IFRS 16, every store lease with a term over 12 months must be capitalised. For a retailer with 30 stores and average annual rent of 100,000 per store, this adds millions to both the asset and liability side of the balance sheet. The impact on net assets, gearing ratios, and lender covenants is material and must be communicated clearly to investors and lenders.
IFRS 15 requires retailers to estimate the proportion of gift cards that will never be redeemed (breakage) and recognise breakage income proportionally as redemptions occur. Recognising all gift card income on sale creates overstated revenue in the year of sale and understated revenue in redemption years. Auditors routinely test gift card accounting as a high-risk area during year-end fieldwork.
IAS 2 requires inventory to be carried at the lower of cost or net realisable value. When NRV falls below cost due to markdown activity, damage, or obsolescence, a write-down is mandatory. Deferring write-downs until year end overstates inventory on the balance sheet and overstates gross margin in the P&L for every interim period. Monthly write-down reviews are the correct treatment.
E-commerce return rates in retail can reach 20 to 30% for clothing categories. Under IFRS 15, revenue can only be recognised to the extent that it is highly probable a significant reversal will not occur. Retailers must estimate expected returns at the point of sale and recognise a refund liability, reducing revenue accordingly. Recognising gross online revenue without a returns provision overstates income and misleads management on actual net revenue performance.
We review every store lease, franchise agreement, and inventory accounting policy before agreeing the engagement scope. We restructure the chart of accounts to support store-level reporting, IFRS 16 lease schedules, and gross margin analysis by product category.
We connect to your point-of-sale system and inventory management platform to pull daily sales and stock movement data into the accounting records each month. This eliminates manual re-keying and ensures the inventory ledger matches the operational stock position.
At each month end we prepare store-level P&L statements, group consolidated accounts, IFRS 16 depreciation and interest journals, inventory write-down assessments, gift card liability updates, and balance sheet reconciliations. Management accounts delivered by the 10th of the following month.
At year end we prepare IFRS-compliant statutory financial statements including IFRS 16 lease disclosures, IAS 2 inventory notes, IFRS 15 revenue accounting policies, and all related party disclosures. We coordinate directly with your auditors to ensure fieldwork completes on time.
Our team understands IFRS 16 for store leases, IAS 2 inventory accounting, IFRS 15 gift card and loyalty treatment, multi-site consolidation, and franchise fee accounting. This is not a generic service applied to a retail client. It is specialist reporting built for the sector.
We connect directly to your point-of-sale and inventory systems to pull daily sales and stock data into the accounting records, eliminating manual re-keying and ensuring the monthly gross margin calculation reflects actual inventory movements.
Unlike generalist providers who prepare only a single group P&L, we produce individual store-level statements from the first reporting period. This allows management to identify underperforming sites and make evidence-based decisions on lease renewals and closures.
Whether you operate a single boutique or a chain of 100 stores, our engagement model scales without adding proportional cost. Store-level reporting and group consolidation are both included within the standard engagement structure.
Every engagement is staffed by qualified accountants with direct retail sector experience. Our team structure ensures continuity, coverage during peak trading periods, and the depth to handle complex year-end and audit requirements without delays.
Outsourced financial reporting for retail businesses covers the preparation of store-level P&L statements, IFRS 16 lease accounting schedules, inventory valuation reports, gross margin analysis by product category, shrinkage and markdown accounting, and IFRS-compliant annual financial statements for single-site and multi-site retailers.
IFRS 16 requires retailers to capitalise all operating leases with a term of more than 12 months as right-of-use assets on the balance sheet, with a corresponding lease liability. This significantly improves reported EBITDA and changes the debt-to-equity ratio. Retailers with large store lease portfolios are materially affected. Cred Books applies IFRS 16 correctly from onboarding day one.
The most common inventory valuation methods for retail are FIFO and Weighted Average Cost. FIFO is generally preferred under IFRS. The Retail Inventory Method is also used by some retailers to estimate inventory values between physical stock counts. Cred Books recommends and applies the method that best reflects the client's inventory flow and satisfies their audit requirements.
Yes. Cred Books prepares individual store-level P&L statements and group-level consolidated accounts for retailers operating multiple locations. Store-level reporting allows management to identify underperforming sites, benchmark stores against each other, and make evidence-based decisions on lease renewals and store closures.
Shrinkage must be recognised as an expense when identified or estimated at period end. Markdowns reduce the net realisable value of affected stock below cost and require a write-down under IAS 2. Cred Books accounts for both systematically at each monthly close, so your gross margin reports reflect the real margin position and not an artificially inflated figure.
Yes. We account for franchise royalty fees, brand marketing fund contributions, and area development obligations for franchised retail operators. We ensure all franchise-related costs are correctly classified in the P&L and disclosed in the notes to the financial statements in the format required by the franchisor agreement.
Cred Books works with Xero, QuickBooks, MYOB, Sage, and NetSuite for retail clients. We integrate with point-of-sale and inventory management systems to pull daily sales and stock movement data directly into the accounting records, eliminating manual re-keying and accelerating the monthly close process.
Ready to Fix Your Retail Financial Reporting?
Talk to a retail reporting specialist. Fixed monthly fee. IFRS-compliant. No lock-in contracts.
Get a Free Consultation