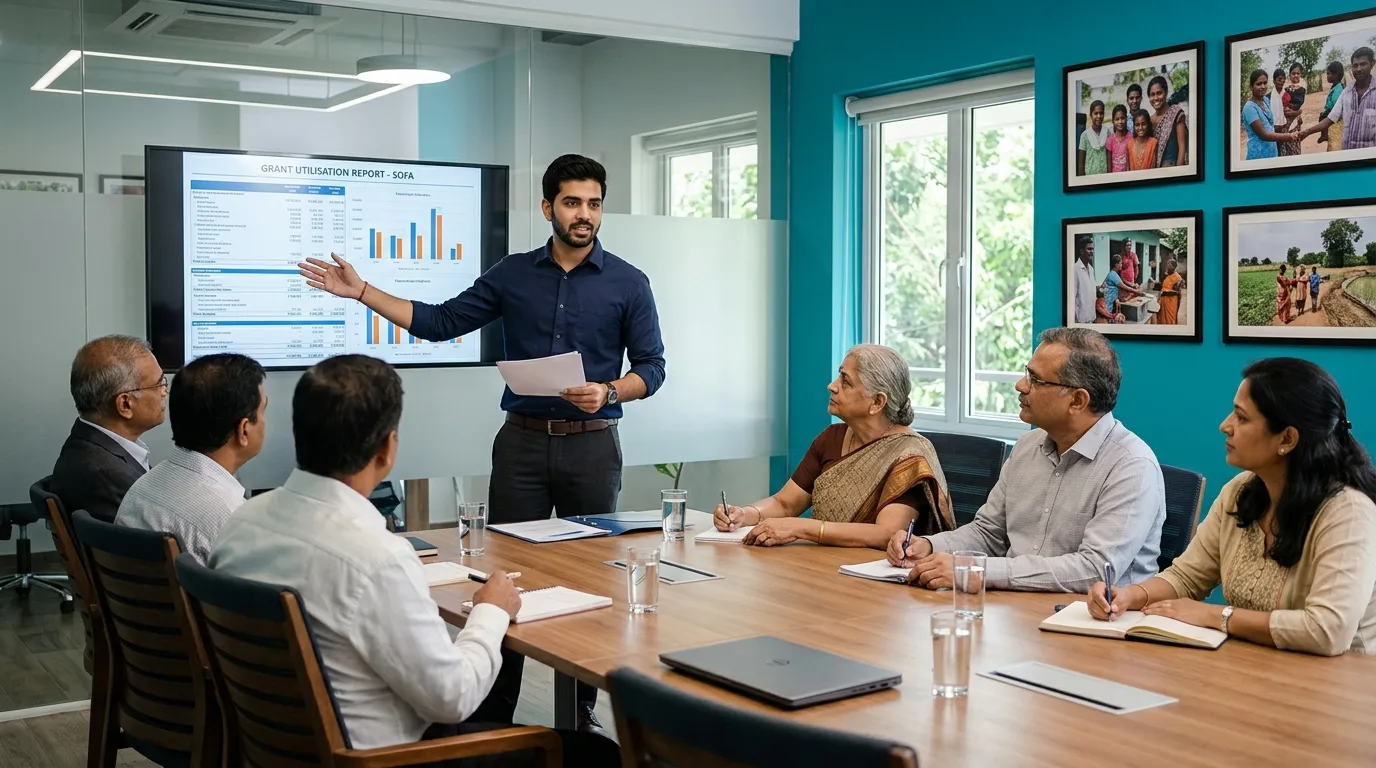
Nonprofit Financial Reporting Services cover the end-to-end preparation of nonprofit management accounts, restricted fund accounting, grant utilisation reports, donor reporting, and Charities SORP compliant statutory financial statements. Rather than attempting to force standard commercial accounting practices onto a charity, nonprofit boards engage Cred Books to deliver accurate, compliant reporting that satisfies funders and regulators on a fixed monthly cycle.
Cred Books has delivered nonprofit financial reporting services for registered charities, NGOs, professional associations, and membership bodies across the UK, Ireland, and Australia. Every client gets reporting that segments restricted funds, tracks endowment fund accounting, and is fully compliant with FRS 102 and the relevant local regulatory framework.
Nonprofit financial reporting is fundamentally different from commercial accounting. A commercial business pools its revenue and measures profit. A nonprofit must segment its income into restricted funds, unrestricted funds, and endowment funds, tracking the expenditure for each separately to prove to donors that their money was spent as intended. Failing to ring-fence restricted funds correctly constitutes a breach of trust and can trigger regulatory intervention.
Beyond fund accounting, nonprofits face Charities SORP compliance, complex grant utilisation reporting requirements from institutional funders, and the need to present a Statement of Financial Activities (SOFA) rather than a simple P&L. An outsourced accounting services provider without specific charity experience cannot handle these obligations. Cred Books builds this compliance into the cloud accounting ledger from day one.
We segment restricted grants and donations within the chart of accounts, ensuring expenditure is matched correctly against the right fund. This prevents cross-subsidisation and gives your board confidence that donor restrictions are being honoured.
Monthly and annual preparation of the SOFA. We present incoming and expended resources horizontally across unrestricted, restricted, and endowment funds, giving trustees a clear view of the charity's true financial position.
Detailed reports comparing actual expenditure against approved grant budgets. We ensure all eligible direct and indirect costs are allocated to the grant so you can draw down funding efficiently without under-claiming or over-claiming.
Customised financial reports prepared in the format required by institutional funders, trusts, and major donors. We map the data directly from the accounting system to the funder's template, ensuring accuracy and saving management time.
Monthly management accounts tailored for boards of trustees. Includes variance analysis against annual budgets, cash flow forecasting, reserve level tracking, and balance sheet reconciliations to support governance decisions.
Complete preparation of the year-end audit file. We reconcile all funds, provide documentation for grant income, and prepare the draft annual financial statements to minimise auditor queries and keep your audit fees under control.
Specialist accounting for expendable and permanent endowment funds. We track investment gains, losses, and income generated by the endowment, ensuring they are allocated correctly under the terms of the original endowment trust.
Systematic allocation of core operating costs (rent, administration, IT) across restricted and unrestricted projects based on a defensible methodology. Ensures you are recovering maximum permitted overheads from your funders.
Preparation of the annual statutory accounts in full compliance with FRS 102 and the Charities SORP, including the Trustees' Annual Report data, reserves policy disclosures, and related party transaction notes.
If a donor gives £50,000 specifically for a new community programme, those funds are legally restricted. They cannot be used to pay general administrative salaries or rent. The accounting system must track that £50,000 independently and match only eligible expenses against it. Failing to do so can result in the charity having to repay the grant.
The Statement of Recommended Practice (SORP) overrides standard commercial accounting principles. It requires incoming resources to be recognised when there is entitlement, probability of receipt, and reliable measurement. It also mandates the SOFA presentation format. An accountant unfamiliar with the SORP will produce accounts that fail the year-end audit.
Nonprofits are expected to hold a level of free reserves to ensure operational continuity, but holding too much unrestricted cash attracts criticism from donors and regulators. The financial reporting function must accurately calculate free reserves (excluding restricted funds and fixed assets) so trustees can defend their reserves policy in the annual report.
Many grants only fund direct project costs, leaving the charity to cover core administrative overheads. Effectively allocating a fair portion of overhead costs to restricted projects is essential for the charity's financial survival. This requires a robust, defensible allocation methodology built into the monthly reporting cycle.
| Reporting Area | In-House Finance Team | Cred Books |
|---|---|---|
| Charities SORP Expertise | Varies; often requires expensive specialist hires | Deep SORP and FRS 102 expertise standard |
| Restricted Fund Accounting | Manual tracking via offline spreadsheets | Systematised tracking within the accounting software |
| Grant Utilisation Reporting | Ad hoc; often reactive when funders ask | Delivered proactively every month |
| Monthly Reporting Speed | Often 15 to 20 working days post-month end | Delivered reliably by the 10th of the following month |
| Audit Preparation | High stress period; disrupts daily operations | Audit-ready files prepared seamlessly |
| Cost Efficiency | High fixed salary overheads for the charity | Fixed monthly fee; better use of donor funds |
For charities reporting under the SORP, the Statement of Financial Activities (SOFA) is mandatory. It groups income and expenditure by activity (e.g., raising funds, charitable activities) rather than by natural classification (e.g., salaries, rent). This requires a chart of accounts that is mapped fundamentally differently from a commercial business.
A restricted fund should generally not be in deficit, as it implies unrestricted funds are cross-subsidising a restricted project without approval. If a deficit occurs due to timing differences in grant receipts, this must be carefully managed and disclosed in the financial statements. Our tracking prevents accidental deficits.
Under FRS 102 and the Charities SORP, material donations of goods, facilities, or professional services (pro bono work) must be recognised in the SOFA as both income and an equivalent expense at their estimated fair value. This ensures the true scale of the charity's operations is reflected in the accounts.
Permanent endowment funds require the capital to be held indefinitely, while the income generated can be spent. Expendable endowments allow the capital to be spent under certain conditions. Accounting for the distinction between capital movements and income generation is critical to avoid breaching trust law.
We review your existing funding agreements, donor restrictions, and regulatory framework. We then restructure your chart of accounts to ensure restricted and unrestricted funds are tracked systematically.
We design a management reporting pack tailored for your board of trustees, including a monthly SOFA, cash flow forecast, and grant utilisation dashboard. We agree on the overhead allocation methodology.
At each month end, we process transactions, perform balance sheet reconciliations, apply overhead allocations, and issue the management accounts pack by the 10th of the following month.
At year end, we prepare the SORP-compliant statutory financial statements, assemble the audit file, and liaise directly with your external auditors to ensure a smooth, query-free audit process.
We don't just apply commercial accounting to charities. We understand the specific requirements of FRS 102, the Charities SORP, and the regulatory expectations of the Charity Commission and institutional funders.
We move restricted fund tracking out of error-prone offline spreadsheets and into the core accounting software, ensuring every pound of restricted income is matched accurately against eligible expenditure.
Trustees need clear, actionable financial data to govern effectively. Our nonprofit management accounts present complex fund movements in a format that non-financial trustees can easily understand and use.
By outsourcing your nonprofit finance function, you eliminate the overhead of recruiting and retaining specialist finance staff, ensuring more of your funding is directed towards your charitable objectives.
Your reporting is handled by qualified accountants. This team depth ensures you have the expertise needed for complex year-end audits without relying on a single in-house employee.
Nonprofit financial reporting services cover the preparation of management accounts, Charities SORP compliant statutory financial statements, restricted fund accounting, grant utilisation reporting, and the Statement of Financial Activities (SOFA) for charities, associations, and NGOs.
When a donor restricts a grant for a specific purpose, the nonprofit must track that income and its associated expenditure separately from general operating funds. This ensures conditions are met, prevents breach of trust, and provides a clear audit trail for the donor.
The Charities Statement of Recommended Practice (SORP) provides the framework for charity accounting in the UK and Ireland. It dictates how charities must prepare annual accounts, including the requirement to produce a Statement of Financial Activities (SOFA) instead of a standard P&L.
We track expenditure against specific grant codes within the ledger. At month end, we produce grant utilisation reports comparing actual spend against the approved budget, ensuring you can demonstrate compliance to funders and draw down funding efficiently.
A SOFA replaces the traditional P&L for charities. It shows all incoming and expended resources, split vertically into unrestricted funds, restricted funds, and endowment funds, giving trustees a complete view of financial movements and fund balances.
Yes. Our charity audit preparation service ensures that all restricted funds are reconciled, grant agreements are documented, and the statutory financial statements are fully compliant with FRS 102 and the Charities SORP before auditors begin fieldwork.
Cred Books works with Xero, QuickBooks, and Sage for nonprofit clients. We use tracking categories and class features within these platforms to manage restricted fund accounting and departmental budgets effectively.
Ready to Fix Your Nonprofit Financial Reporting?
Talk to a charity reporting specialist. Fixed monthly fee. SORP-compliant. No lock-in contracts.
Get a Free Consultation