Request Callback

Outsourced Financial Reporting for Educational Institutes

What Is Outsourced Financial Reporting for Educational Institutes?

Outsourced financial reporting for educational institutes covers the end-to-end preparation of management accounts, tuition fee deferred revenue schedules, department budget variance analysis, grant and endowment accounting, and education regulatory reporting. Rather than relying on an administrative team to handle complex financial reconciliations, schools, colleges, and trusts engage Cred Books to deliver accurate reporting on a fixed monthly cycle.

Cred Books has delivered reporting for independent schools, Multi-Academy Trusts (MATs), higher education providers, and vocational colleges across the UK, Ireland, Australia, and the UAE. Every client gets reporting that separates restricted funding from operational revenue, providing governors and trustees with the financial clarity needed to make strategic decisions.
Outsourced financial reporting for educational institutes

Why Education Financial Reporting Requires Specialist Knowledge

Financial reporting in education is dominated by timing differences. Academic years rarely align neatly with statutory financial years. Tuition fees collected in August must fund operations through to July of the following year. If an institute simply recognises cash when it is received, its accounts will show massive artificial profits in autumn and severe artificial losses in spring. Correctly amortising tuition fee deferred revenue requires systemic discipline.

Beyond revenue recognition, educational institutes must navigate restricted government funding, complex teacher pension scheme accounting, faculty budgeting, and the demands of education regulatory reporting (e.g., ESFA returns in the UK). An outsourced accounting services provider without sector experience will struggle to map these obligations effectively. Cred Books understands the unique rhythms of the academic financial cycle. Our broader financial reporting services span multiple sectors, including nonprofit organisations.

Why education financial reporting requires specialist knowledge

Education Financial Reporting Services We Deliver

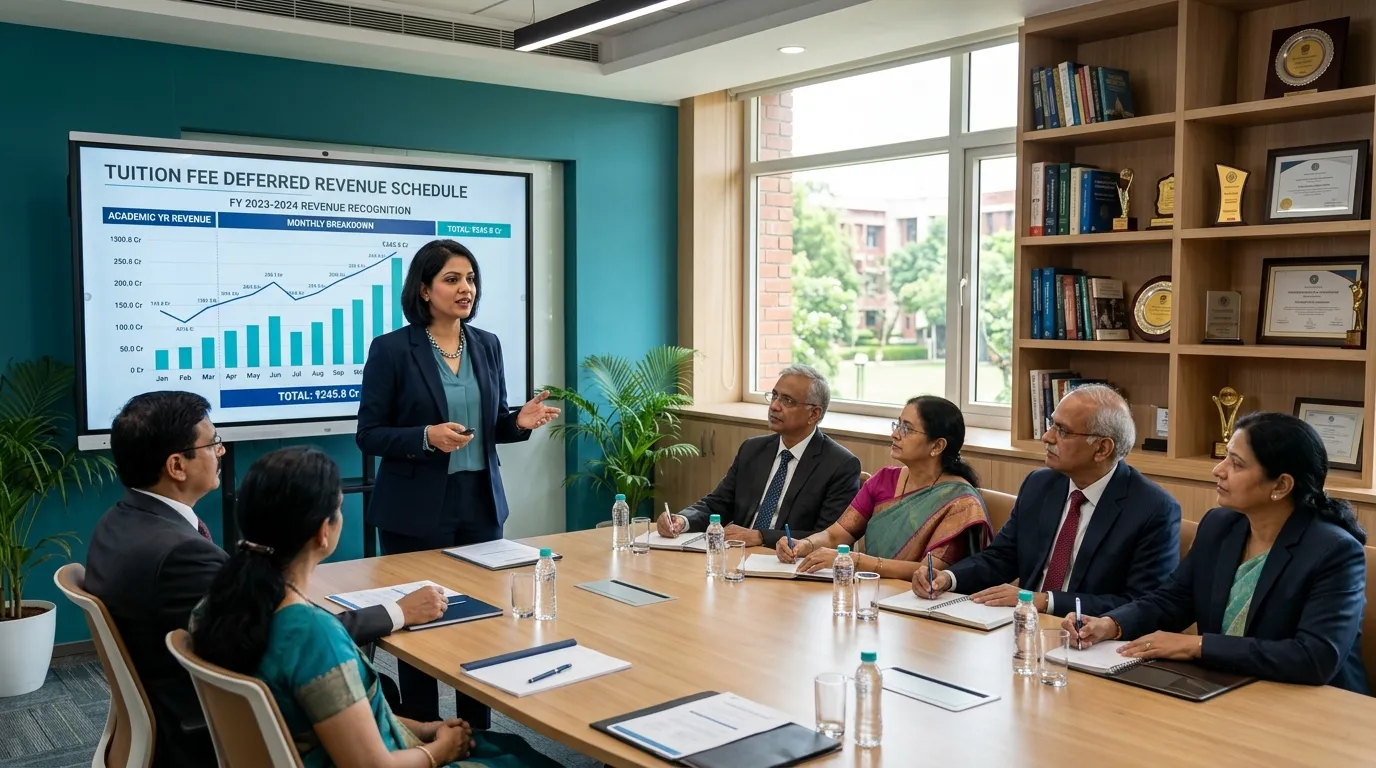
Tuition Fee Deferred Revenue

We manage the complex process of deferring annual or termly tuition fee receipts, amortising the revenue evenly over the academic teaching periods to ensure the monthly P&L reflects true operational performance.

Department Budget Variance

We track expenditure by faculty, department, and cost centre. We provide department heads with specific monthly reports showing their actual spend against budget, enforcing financial accountability across the institute.

Multi-Academy Trust (MAT) Consolidation

For MATs, we provide consolidated reporting that rolls up the financials of individual schools into a single trust view, managing inter-school transfers and top-slice central service fees smoothly.

Grant Accounting

We segment restricted government funding (e.g., Pupil Premium, specific capital grants) within the ledger. We match eligible expenses against these funds to ensure compliance with funding body regulations.

Endowment Accounting

Specialist accounting for independent school and university endowments. We track the capital value of the endowment, allocate investment income, and ensure distributions comply with the terms of the specific trusts.

Student Funding Reconciliations

We reconcile student loan company receipts, bursaries, and scholarship allocations against individual student accounts, ensuring the ledger matches the student management system exactly.

Academic Year vs Financial Year Reporting

We bridge the reporting gap, delivering management accounts based on the academic year for operational management, while preparing statutory accounts based on the required legal financial year.

Education Regulatory Reporting

We prepare the financial data required for sector-specific regulatory submissions, such as ESFA returns for UK academies, ensuring data is formatted correctly for smooth compliance filing.

Statutory Financial Statements

Preparation of the annual financial statements in full compliance with the Charities SORP (where applicable) or standard corporate GAAP, ready for your external auditors.

Why Education Financial Reporting Is More Complex Than Standard Business Reporting

The September Cash Spike is Deceptive

Independent schools and universities often receive the bulk of their cash for the year in August and September. A standard P&L would show the institution as wildly profitable in Q3 and heavily loss-making for the rest of the year. Effective reporting must spread this revenue to match the delivery of education.

Bursaries and Scholarships Muddle Revenue

If a school charges £15,000 in fees but grants a £5,000 scholarship, accounting rules dictate how this is recorded. Usually, it must be recorded as £15,000 gross revenue and £5,000 expense, rather than £10,000 net revenue. Mishandling this distorts the top-line growth metrics of the institute.

Consolidating Disparate Sites is Difficult

Multi-Academy Trusts (MATs) or university groups operate across multiple sites, often using different local processes. Consolidating this data into a single Trust-level report—while eliminating inter-school transactions like shared staff costs or central top-slices—is highly complex and prone to spreadsheet errors.

Fund Accounting Rules Apply

Like charities, educational institutes often receive restricted funds. A government grant for a new science block cannot be spent on English department salaries. The accounting system must ring-fence these funds and track specific expenditure against them to prove compliance to auditors.

In-House Finance Team vs. Cred Books for Education Financial Reporting

Reporting AreaIn-House Finance TeamCred Books
Deferred Revenue TrackingManual tracking via offline spreadsheetsSystematised tracking within the general ledger
Department Budget VarianceAd hoc; often provided only on requestDelivered proactively every month to faculty heads
MAT ConsolidationPainful monthly process prone to errorsAutomated consolidation via advanced reporting tools
Management Accounts DeliveryOften delayed by internal administrative dutiesDelivered reliably by the 10th of the following month
Audit PreparationCauses significant disruption to school operationsAudit-ready files prepared seamlessly in the background
ScalabilityRequires new finance staff as student numbers growFixed monthly fee; scales efficiently with your growth

Key Facts About Education Financial Reporting

Charities SORP May Apply

Many independent schools and universities are registered charities or exempt charities. This means their statutory reporting must comply with the Charities SORP, replacing the standard P&L with a Statement of Financial Activities (SOFA) and enforcing strict fund accounting.

Pension Accounting is Complex

Educational institutes often participate in multi-employer defined benefit pension schemes (like the Teachers' Pension Scheme in the UK). Accounting for these liabilities, especially when taking on new schools in a MAT, requires specialist knowledge of FRS 102 section 28.

Capital Grants vs Revenue Grants

A grant provided to build a new sports hall (capital grant) is treated differently from a grant provided to subsidise school meals (revenue grant). Capital grants are often deferred and released to the P&L over the useful life of the asset built.

Trading Subsidiaries Protect Charitable Status

If an independent school generates significant income from non-charitable activities (e.g., renting out facilities for weddings, running a commercial sports club), this is often run through a wholly-owned trading subsidiary. The financial reporting must consolidate these entities at year-end.

Get Accurate Education Financial Reporting on a Fixed Monthly Cycle

Cred Books delivers tuition fee deferred revenue tracking, grant accounting, and MAT consolidation for ambitious educational institutes.

Get a Quote

How We Onboard an Education Financial Reporting Client

1

Revenue & Grant Audit

We review your tuition fee structure, bursary policies, and restricted grant funding. We map how data will flow from your student management system (e.g., SIMS, iSAMS) to the general ledger.

2

Reporting Design

We design a management reporting pack tailored for your board of governors, including academic year performance, cash flow forecasting, department variance, and consolidated MAT views where applicable.

3

Monthly Cycle & Accruals

At month end, we process transactions, apply tuition fee deferred revenue journals, perform balance sheet reconciliations, and issue the management accounts by the 10th of the following month.

4

Audit and Statutory Reporting

At year end, we prepare the statutory financial statements, manage the audit file, and prepare the data required for education regulatory reporting bodies (e.g., ESFA).

Why Choose Cred Books for Education Financial Reporting?

Education Sector Specialists

We understand the difference between academic and financial years, the intricacies of the Charities SORP, and the specific demands of Multi-Academy Trust accounting. You won't have to train us.

Systematised Revenue Recognition

We move deferred revenue tracking out of offline spreadsheets and into the core accounting software, ensuring every pound of tuition fee is recognised in the correct operational month.

Board-Ready Reporting

Governors and trustees need clear, actionable financial data to govern effectively. Our management accounts present complex fund movements and MAT consolidations in a highly readable format.

Cost-Effective Scalability

By outsourcing your education finance function, you eliminate the overhead of recruiting specialist finance staff, allowing you to direct more funding towards front-line teaching and student facilities.

Integration Experts

We integrate modern cloud ledgers like Xero and QuickBooks with your existing education management software, reducing manual data entry and improving accuracy.

Why choose Cred Books for education financial reporting

Frequently Asked Questions About Education Financial Reporting

It involves managing tuition fee revenue recognition, grant fund accounting, departmental budgeting, and statutory reporting for schools, colleges, academies, and universities on an outsourced basis.

When a student pays an annual fee upfront, we record it as a deferred liability and amortise it evenly over the academic teaching months, ensuring the P&L reflects true operational performance.

Yes. We bridge the gap, delivering management accounts based on the academic year for governors, while preparing the statutory accounts based on the required legal financial year.

Absolutely. For MATs, we track the performance of individual academies and consolidate them into a single trust-wide reporting pack, including the treatment of inter-school transfers and top-slice fees.

We segregate restricted government grants within the ledger. We match eligible expenditures against these specific funds to prevent cross-subsidisation and ensure compliance with the funder's terms.

Yes. We provide faculty heads with specific monthly reports showing their actual spend against their allocated annual budget, allowing them to manage resources effectively.

We use cloud platforms like Xero, QuickBooks, and NetSuite, integrating them with student management systems (like SIMS or iSAMS) to streamline fee collection and reporting without manual data entry.

Ready to Fix Your Education Financial Reporting?

Talk to an education finance specialist. Fixed monthly fee. MAT consolidation ready. No lock-in contracts.

Get a Free Consultation